 admin
Managing money effectively is one of the most vital skills you can develop in life. Regardless of your income level, knowing how to track, save, and invest your hard-earned funds dictates your long-term financial stability. Many people struggle with financial anxiety not because they do not earn enough, but because they lack a structured system to manage their resources. Here are five practical steps to take control of your financial destiny today.
1. Build a Purposeful Budget
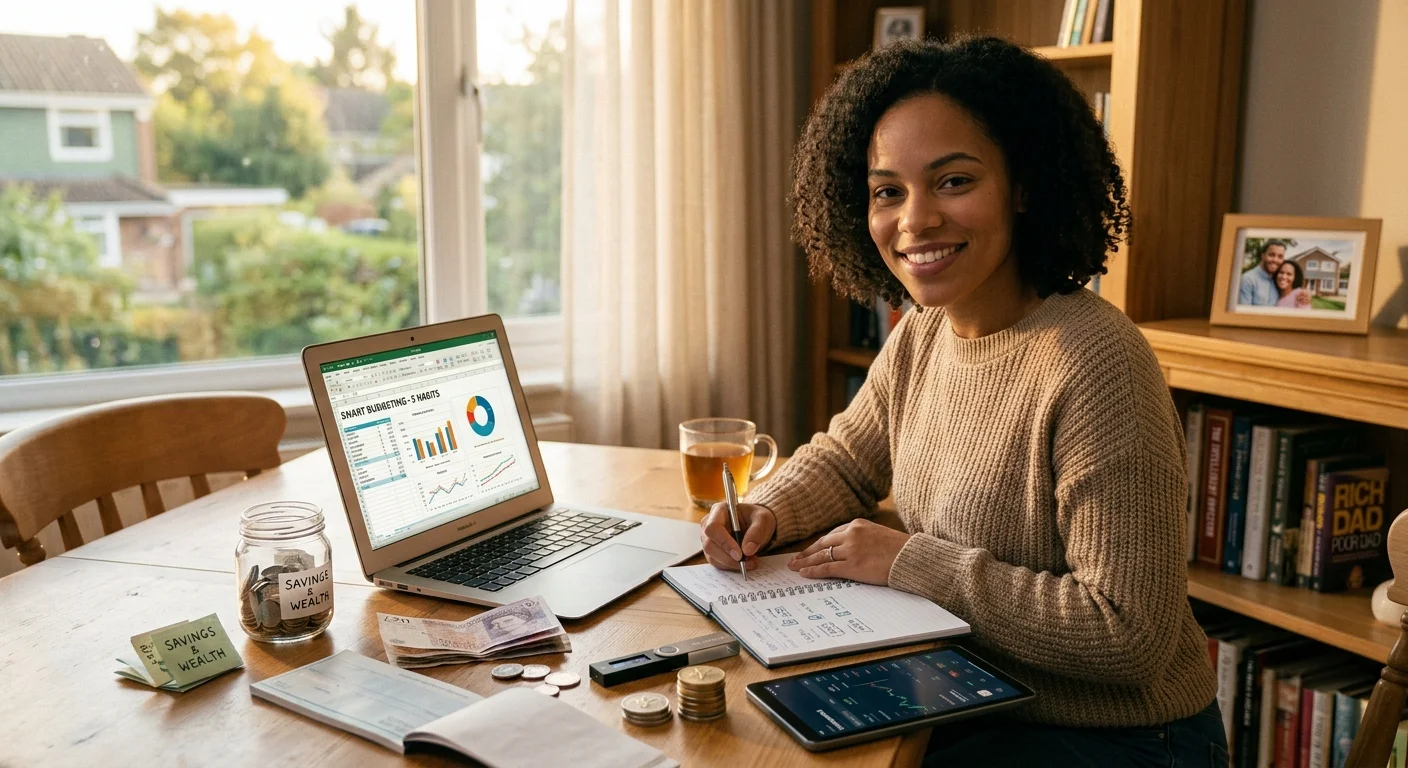
A budget is not a tool of restriction; it is a roadmap to financial freedom. The classic 50/30/20 rule is an ideal framework to get started. Allocate 50% of your net income toward necessary living expenses like rent and groceries, 30% toward personal wants and entertainment, and dedicatedly send 20% directly into savings and investments. Keeping track of your regular cash flow reveals unnecessary leaks, such as unused subscriptions or impulse purchases.
2. Establish an Emergency Fund First
Life is unpredictable, and sudden unexpected expenses—such as medical urgent care or sudden job transitions—can easily push you into high-interest debt. Prioritize building an emergency buffer containing three to six months worth of basic living expenses. Keep this money in a liquid, easily accessible high-yield savings account so it remains secure and available when you truly need it.
3. Eliminate High-Interest Debt
Carrying credit card debt or high-interest loans is a major barrier to building real wealth. The compound interest on consumer debt rapidly works against your progress. Use proven debt repayment strategies like the Debt Avalanche (paying off the highest interest rate first to save total money) or the Debt Snowball (paying off the smallest balance first for psychological momentum). Pay more than the minimum payments to clear your debt quickly.
4. Make Automating Savings a Priority
Relying purely on willpower to save whatever money remains at the end of the month rarely works. Instead, pay yourself first. Set up automated transfers on your payday that automatically move funds into your savings or investment accounts. By automating this process, saving becomes a consistent habit without requiring constant effort or second-guessing.
5. Invest for the Long Term
Saving money alone will not build wealth, as inflation steadily erodes purchasing power over time. Put your money to work by investing in long-term financial assets such as index funds, mutual funds, or real estate. The power of compound interest rewards those who start early and stay consistent. Consistent, disciplined contributions over a decade or two yield significantly higher returns than trying to time the market.
Final Thoughts
Achieving financial independence is a continuous marathon, not a quick sprint. You do not need a degree in finance to make smart decisions—you simply need discipline, consistent habits, and patience. Start small today by creating a basic budget, and watch your financial security grow step by step.